
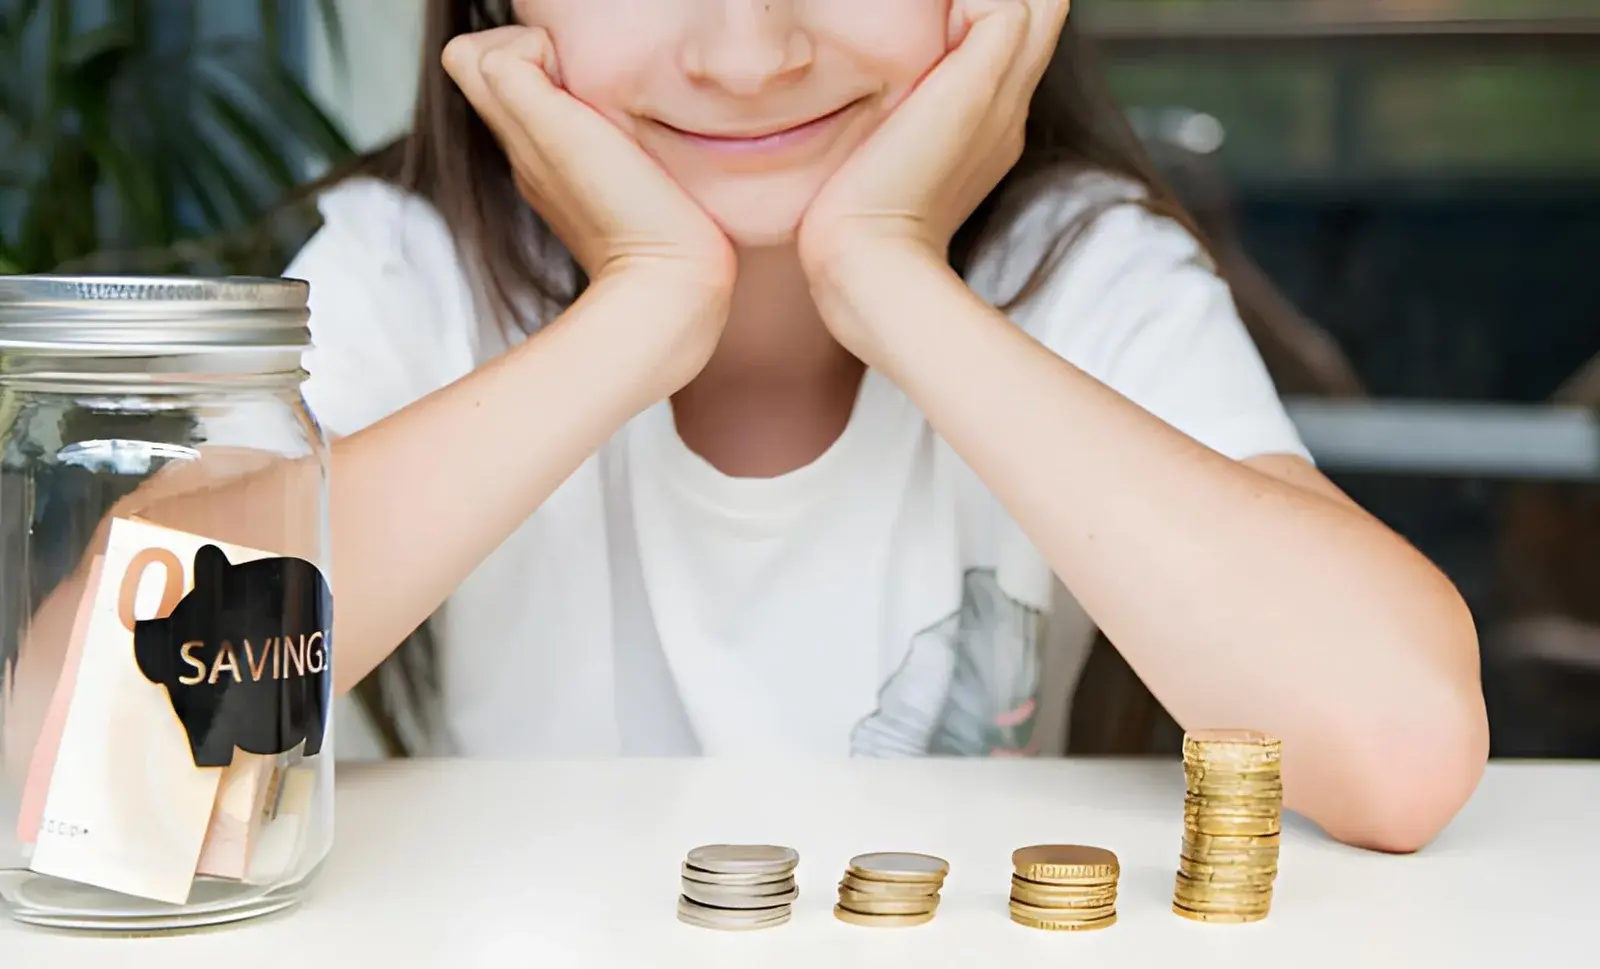
A kid does not need a huge allowance or a fancy teen card to start learning real credit habits. In many cases, a very small limit works better. A tight cap turns money into something visible. It creates a natural pause before swiping again, which is exactly where judgment starts to grow.
That matters because the lesson is not really about buying power. It is about restraint, timing, and attention. Adults usually think of credit as access to more money. Kids often experience it as delayed consequences. A small limit keeps those consequences manageable while still making them real. Even families comparing options as different as a starter card, a debit account, or a title loan in Janesville can use the same basic idea. The smaller the margin for error, the clearer the lesson.
A low limit also changes the conversation at home. Instead of asking, “Can you handle a card?” parents can ask, “Can you plan for one purchase, leave room for a surprise, and pay it off on time?” That is a much better test of readiness than whether a teenager can memorize a list of financial terms.
Why a small limit teaches better than a generous one
Big limits can hide sloppy habits for a while. A kid can overspend, carry a balance, or forget what is already charged without feeling immediate friction. Small limits make those mistakes show up faster. That feedback loop is useful.
For example, a teen with a very low limit learns quickly that buying concert tickets on Monday might mean not having room for gas on Thursday. That is not just budgeting. It is prioritizing under pressure. It teaches that every choice closes off another choice.
A low limit also highlights how credit works differently from cash. With cash, the pain comes first because the money is gone right away. With credit, the fun comes first and the bill comes later. Young people often need practice connecting those two moments. The shorter the runway, the easier it is to see the connection.
The hidden habit is not spending less, it is monitoring more
One overlooked benefit of a small credit line is how often it encourages checking the account. A teen with a narrow limit has a reason to look at the balance, pending charges, and due date regularly. That routine matters as much as the purchases themselves.
The Consumer Financial Protection Bureau explains that credit cards involve terms like interest rates, changing terms, and billing rules that borrowers need to understand before problems start. A simple family system built around credit card basics from the CFPB can help kids connect each purchase to a statement, a deadline, and a consequence.
Low limits create better conversations about utilization
Another practical lesson is credit utilization, which sounds technical but is easy to explain. It is simply how much of the available credit is being used. If a kid has a $300 limit and charges $240, that card is mostly full even if the purchase was affordable in a broader sense.
According to myFICO’s explanation of amounts owed and utilization, using a high percentage of available revolving credit can hurt credit scores, while lower utilization can be viewed more favorably. For teenagers and young adults, this creates an important distinction. A purchase can be paid back eventually and still be unwise if it consistently pushes the account near its ceiling.
That makes low limits a good teaching tool, but only if adults explain the lesson clearly. The point is not to scare kids away from credit. The point is to show that a card has two jobs at once. It helps make purchases, and it quietly records patterns.
How families can use a small limit without turning it into a trap
- Put only one or two repeat expenses on the card.
- Set a personal spending ceiling below the actual limit.
- Review the account once a week, not just when the bill arrives.
- Pay the full statement balance whenever possible.
- Treat one mistake as a lesson, not a character verdict.
That last point matters. Kids learn best when correction is immediate and specific. “You forgot the due date” is useful. “You are bad with money” is not. Small credit limits are effective because they make the problem small enough to discuss calmly.
The goal is judgment, not access
A first credit experience should not prove that a teen can spend. It should prove that they can pause, track, and recover. A small limit supports all three. It turns every purchase into a tiny planning exercise and every payment date into a habit checkpoint.
Over time, those habits matter more than the number on the account. Financial maturity usually looks boring from the outside. It is checking balances, leaving cushion, paying on time, and not treating available credit like available income. Small limits teach that early, and that is a big lesson to learn while the stakes are still small.
Also Read
